
Dynamic Share Allocation Mechanics During Founding Team Operational Restructuring
Dynamic share allocation adjusts equity distribution among founding members based on continuous risk, cash, and time contributions during operational shifts.
Dynamic share allocation adjusts equity distribution among founding members based on continuous risk, cash, and time contributions during operational shifts.
Sweat equity converts to seed equity when unquantified historical labor is priced into a pre-money cap table and subjected to institutional option pool dilution.
Buyout valuations balance foundational code longevity against live operational refactoring burden to determine final equity settlement prices.
Capitalization table restructuring recalibrates historical equity allocations when legacy software deprecation forces costly codebase replacement.
Institutional financing forces informal contributor help onto the formal stock ledger, converting unstated relational expectations into binary equity claims.
Early unpriced technical work converts to equity via IP assignments and restricted stock, separating historical value from ongoing voting control.
Unquantified technical work performed before incorporation converts informal goodwill into retroactive equity claims when legal entities establish fixed capitalization tables.

Convertible note covenants force informal unquantified cofounder labor into binding written releases or explicit cap table allocations.
Early execution signals expose discrepancies between unstated operational expectations and active contributions before foundational agreements lock cap tables.
Unstated relational debts must be severed from statutory stock issuances using explicit corporate contracts to avoid destructive interpersonal capitalization deadweight.
Dynamic multiplier frameworks translate unbilled pre-incorporation labor hours into defensible equity shares by indexing foregone wages against venture risk.
Governance clauses formalize unquantified relational contributions by creating discretionary equity pools and retrospective waivers without converting social capital into debt.
Converting informal startup obligations requires identifying unstated commitments early and resolving unwritten equity pledges before formal legal integration.
Automated valuation software converts unquantified founder reciprocity into cardinal equity metrics, formalizing capitalization records while destabilizing informal trust baselines.
Statutory asset transfers formalize property ownership, converting unquantified sweat equity into fixed legal claims and overriding implicit founder expectations.
Adjusting cofounder equity divisions requires pre-established contractual triggers, explicit milestone vesting, and board authority to repurchase unvested shares upon performance breaches.
Early intellectual property assignments legally consolidate pre-incorporation assets while unbilled founder labor remains an unquantified social debt.
Early startup equity allocation converts tracked capital, market-rate labour, and milestone execution into vested shares protected by time-based forfeiture.
Preincorporation equity claims are resolved by converting unquantified early contributions into market-rate cash obligations or signed release waivers before incorporation.
Tax valuations defend secondary market haircuts against regulatory option volatility by using empirical platform trades to override theoretical model inflation.
Option pricing breakpoint adjustments calculate fair common value under senior overhang by modeling liquidation waterfalls as sequential call option strikes.
Section 351 defers equity exchange taxes when early contributors transfer recognized property rights rather than service labor to achieve eighty percent entity control.
Unstated contribution expectations create covert contracts that distort static founder equity splits, requiring dynamic vesting and explicit terms to prevent cap table breach.
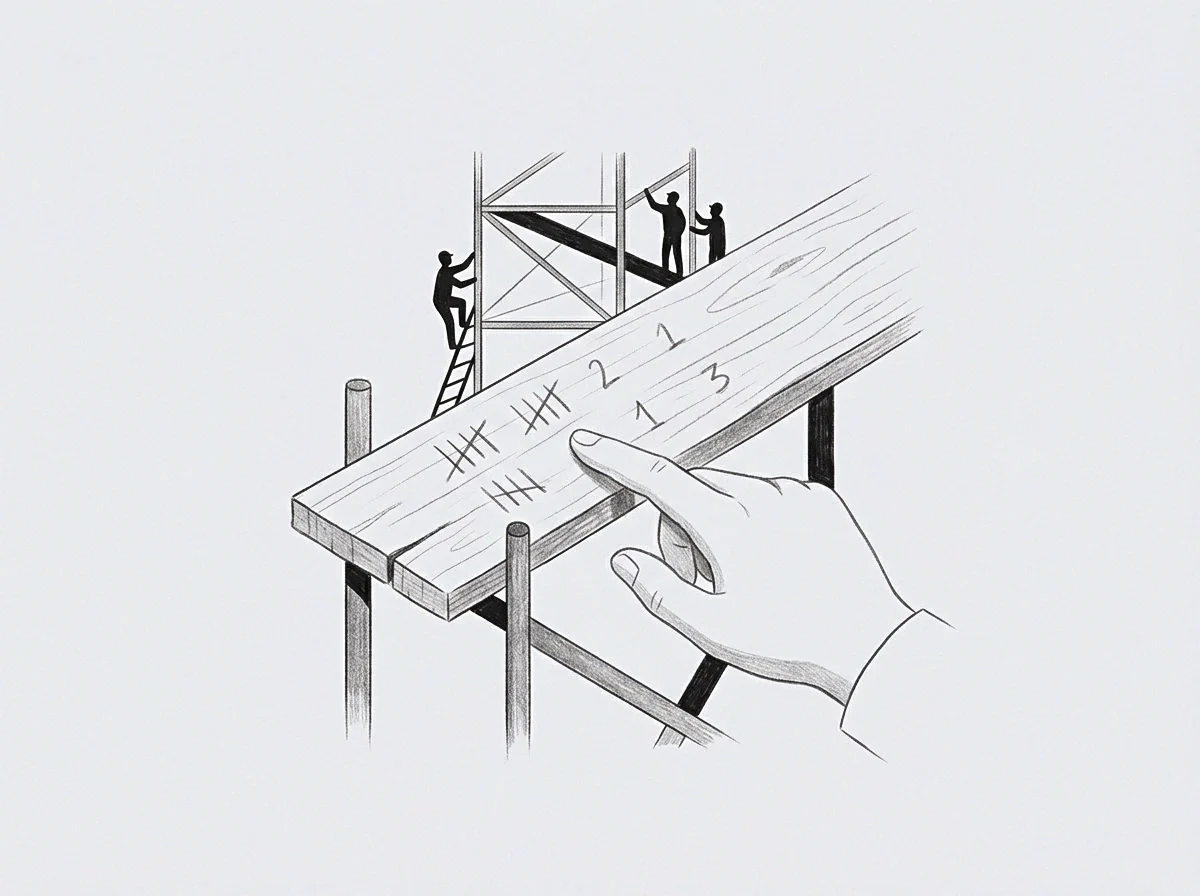
Pre-incorporation sweat equity relies on market shadow salaries and risk multipliers to convert unpaid labor into formal ownership percentages at incorporation.

Tracking pre-incorporation hours transforms generalized reciprocity into an explicit debt that requires formal conversion into equity terms.
The terms are written where they belong. Each field holds three desks, and every entry a desk writes raises the terms it uses, each term given a meaning, a mechanism and the places it appears. The record on these pages stays first person and hand made; the fields grow the nomenclature.